
EU VAT SME Scheme vs OSS vs IOSS: Key Differences in 2026
EU VAT SME Scheme vs OSS vs IOSS: Key Differences in 2026
Three schemes, three jobs. Businesses selling across European borders routinely mix them up, and the mistake is expensive. One is a VAT exemption. One simplifies how you declare VAT you still owe. One handles VAT on low-value imports. They are not alternatives to each other.
Here is the distinction in one line each. The SME Scheme lets a qualifying small enterprise stop charging VAT on eligible supplies. The One Stop Shop lets you declare and pay VAT you do owe on eligible B2C transactions through a single return. The Import One Stop Shop collects VAT at checkout on eligible imported consignments of no more than EUR 150.
Quick Answer. If you are established in the EU, your Union-wide turnover stays under EUR 100 000, and you stay under the national threshold in each country where you want relief, the cross-border SME exemption may apply there. If you sell goods or digital services to EU consumers and owe destination VAT, the Union OSS return is usually the efficient route. If you ship goods into the EU from outside it in consignments up to EUR 150, IOSS is the relevant mechanism. Many businesses use more than one, in different countries, for different transactions.
*As of October 2026. Rules verified against European Commission guidance.*
EU VAT SME Scheme vs OSS vs IOSS — Comparison Table
The table sets the three regimes side by side. Read down the “Main purpose” row first — that single distinction prevents most errors.
| Criterion | SME Scheme | OSS (Union and non-Union) | IOSS (import scheme) |
| Main purpose | VAT exemption on eligible supplies | Simplified declaration of VAT that is due | VAT collection and reporting on eligible imports |
| Eligible businesses | Small enterprises meeting turnover tests | Taxable persons making eligible B2C supplies | Suppliers and electronic interfaces making eligible distance sales of imported goods |
| Establishment requirement | EU establishment required for the cross-border scheme | Union scheme for EU-established; non-Union scheme for non-EU-established | EU or non-EU; non-EU suppliers generally need an intermediary |
| Covered transactions | Eligible supplies of goods and services in participating Member States | Intra-Community distance sales and eligible B2C services | Distance sales of goods imported from outside the EU |
| Main threshold | EUR 100 000 Union turnover, plus national thresholds | EUR 10 000 place-of-supply threshold, where conditions are met | EUR 150 intrinsic value per consignment |
| VAT charged to customers | No, on exempt supplies | Yes, at the destination rate | Yes, at checkout |
| Exemption available | Yes, that is its function | No | No |
| Registration route | Prior notification in the Member State of establishment | Registration in one Member State of identification | Registration in one Member State of identification |
| Identifier issued | EX number | OSS registration under a VAT identification number | IOSS VAT identification number |
| Reporting frequency | Quarterly turnover report | Quarterly return | Monthly return |
| Input VAT deduction | Generally lost on exempt supplies | Preserved under normal rules | Preserved under normal rules |
| Compatibility | Coexists with Union OSS, but not in the same jurisdiction; mutually exclusive with IOSS | Coexists with SME in other jurisdictions and with IOSS | Coexists with OSS; not with the SME Scheme |
| Typical use case | Small EU seller avoiding VAT registration abroad | EU retailer selling goods across several Member States | Non-EU seller shipping low-value parcels to EU consumers |
| Common restriction | No deduction of input VAT; national eligibility must be checked per country | Does not replace local registration where stock is held | Excise goods excluded; consignments above EUR 150 excluded |
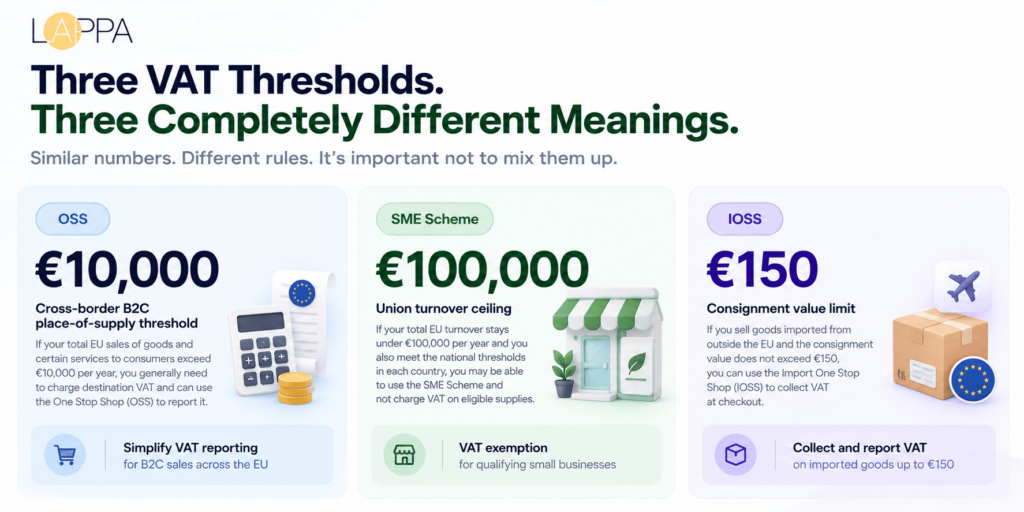
One warning belongs here rather than later. EUR 10 000, EUR 100 000 and EUR 150 measure completely different things: a place-of-supply trigger, an eligibility ceiling, and a per-consignment value limit. Treating them as interchangeable is the most common error we see.
What Is the EU VAT SME Scheme?
The EU VAT SME scheme is a VAT exemption, not a filing simplification. A qualifying small enterprise does not charge VAT on its exempt supplies. In exchange, it generally cannot deduct input VAT relating to those supplies.
Two layers exist. The domestic exemption has long allowed a Member State to exempt small businesses established on its own territory. Since 1 January 2025, the cross-border extension lets a qualifying enterprise apply the exemption in other Member States too, under Council Directive (EU) 2020/285. The Commission’s cross-border SME scheme guidance sets out the conditions in detail.
Entering the Cross-Border SME VAT Scheme
Access to the cross-border SME VAT scheme depends on two tests passing at the same time, not one.
- Union annual turnover across all 27 Member States must not exceed EUR 100 000 in the current and the previous calendar year.
- The national annual threshold, or sectoral threshold, must not be exceeded in each Member State where you want the exemption — in the current and previous calendar years, or the two previous years where a Member State sets it that way.
National thresholds vary and cannot exceed EUR 85 000, and the Commission’s SME scheme portal publishes the national rules country by country. That is why qualifying at home guarantees nothing abroad. A business comfortably under the Union ceiling can still be ineligible in a specific country whose threshold sits far lower.
You file one prior notification, and only in your Member State of establishment, which then acts as your contact point with the others. The notification identifies your business, names the Member States where you want the exemption, and states your supply values for the relevant years.
The EX Number and When the Exemption Starts
Approval produces an EX number. The Commission indicates the process should normally take no longer than 35 working days from receipt of the prior notification, though anti-evasion checks can extend it.
Timing matters more than most sellers expect. The exemption applies from the date your Member State of establishment grants the EX number and confirms it can be used in the selected country — not from the date you filed. The Commission’s own example: a notification submitted on 3 February 2025, confirmed on 5 March 2025, produces a commencement date of 5 March 2025.
How the SME VAT Exemption Works in Practice
Using the SME VAT exemption brings one reporting obligation that surprises people. You file a single quarterly report in your Member State of establishment, disclosing turnover in all 27 Member States — including countries where you never applied the exemption, and including zeros where you had no activity. It is due within one month of the quarter end, so Q1 is reported in April and Q4 in January.
Take a worked example. A Dutch online retailer has EUR 65 000 of Union-wide turnover, selling into Belgium, Germany and Greece. The EUR 100 000 ceiling is not a problem. Eligibility still has to be assessed country by country, because Greece’s national threshold is markedly lower than Italy’s. Turnover below EUR 100 000 grants nothing automatically.
The catch: the exemption covers your outgoing supplies. It does not switch off VAT on what you buy. Reverse-charge VAT on intra-EU acquisitions still applies, and because you are exempt, you generally cannot recover it.
Exceeding a limit has graduated consequences. Pass a national threshold and you are excluded in that country, with the EX number deactivated there. Pass EUR 100 000 of Union turnover and you are excluded everywhere, though your domestic exemption may survive if you still qualify at home. Member States may allow a transitional period — 10%, 25%, or no specific ceiling up to EUR 100 000 — and a quarantine period of one or two calendar years can follow exclusion.
One structural limit is easy to miss. You cannot apply the scheme in a Member State where you hold a fixed establishment, unless that establishment is deregistered for VAT purposes.
What Is the VAT One Stop Shop (OSS)?
The VAT One Stop Shop does not reduce the VAT you owe. It reduces the number of places you file. You register in one Member State of identification and declare, through one return, VAT due in other Member States of consumption.
Three schemes sit under the OSS umbrella since 1 July 2021. The Union scheme serves taxable persons established in the EU, covering intra-Community distance sales of goods and B2C services supplied in Member States where they are not established. The non-Union scheme serves businesses with no establishment in the EU, for B2C services. The import scheme is IOSS, covered in the next section.
Returns are quarterly for the Union and non-Union schemes, with the filing and payment mechanics set out in the Commission’s declare and pay guidance. Two points often get missed. OSS returns are additional to your domestic VAT return, not a replacement. And the scheme is all-or-nothing: once you opt in, you must declare every supply falling under it, in every relevant Member State. Cherry-picking countries is not available.
Understanding the EUR 10 000 Threshold
The EUR 10 000 figure is a place-of-supply threshold, not a registration exemption. Three conditions must all hold: you are established in only one Member State; you supply telecommunications, broadcasting and electronic services to consumers in another Member State, or dispatch goods from your Member State of establishment to another; and the combined total stays at or below EUR 10 000, excluding VAT, in the current and preceding calendar year.
Stay inside it and those supplies follow your own country’s VAT rules. The Union OSS is simply not relevant, because the supplies count as domestic. Exceed it and destination rules apply without exception. You may also opt into destination treatment voluntarily, and that choice binds you for two calendar years.
A practical scenario. A Polish retailer dispatching from Poland passes EUR 10 000 of combined cross-border B2C sales in March. From that supply onward, VAT follows the customer’s country — French VAT on French sales, German VAT on German sales. Union OSS lets the business report all of it in Poland instead of registering in each destination.
When EU VAT Registration Is Still Required
OSS does not dissolve every local obligation, and treating it as a universal replacement causes real problems. Separate EU VAT registration typically remains necessary where you hold stock in another Member State.
That is the Amazon FBA trap. Store inventory in Germany, Poland and Czechia, and those countries generally expect local VAT numbers. Domestic supplies, where dispatch and delivery occur in the same Member State, cannot be declared in the Union scheme by an ordinary supplier. Intra-EU distance sales dispatched from that stock to other countries can be.
What Is the Import One Stop Shop (IOSS)?
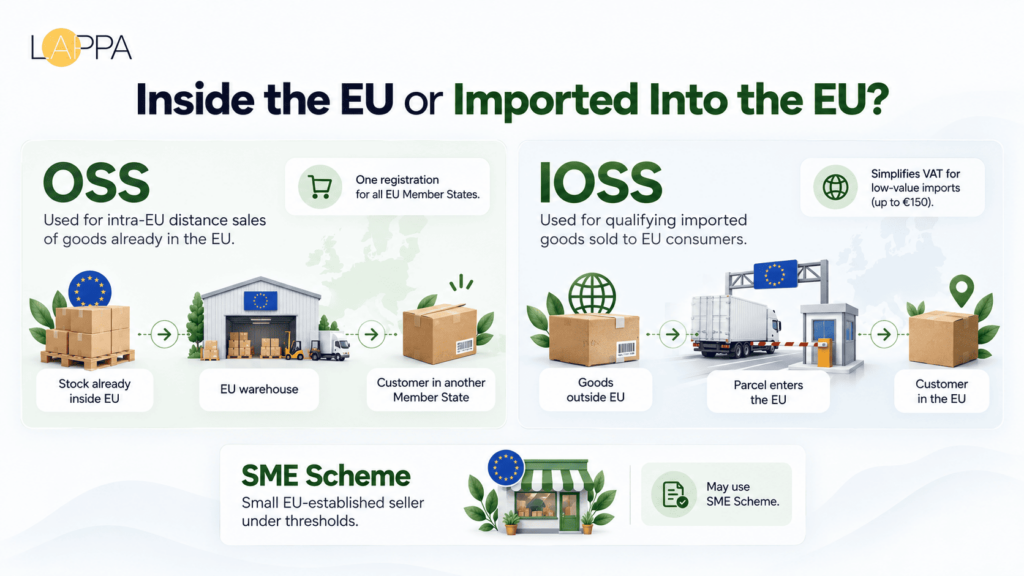
The Import One Stop Shop applies to distance sales of goods imported from outside the EU, in consignments with an intrinsic value not exceeding EUR 150. Excise goods are excluded. Goods already sitting in an EU warehouse do not qualify, because they are not imports.
The mechanism is straightforward. You charge VAT at the destination rate at checkout, quote your IOSS number in the customs declaration, and the consignment clears without import VAT being collected again at the border. Returns are monthly. Done correctly, the customer pays once and receives no surprise invoice from the carrier.
Registration differs by establishment. An EU-established business can register directly. A business established outside the EU generally has to appoint an EU-established intermediary, who becomes liable for the VAT obligations and receives a separate IOSS number for each represented taxable person. Marketplaces complicate this further: an electronic interface facilitating imports of EUR 150 or less to consumers is treated as the deemed supplier and uses its own IOSS number.
Consider a US Shopify merchant shipping EUR 80 to EUR 120 consignments to EU consumers. With IOSS, VAT is charged at checkout and the parcel moves through customs without further VAT collection. Without it, import VAT falls due on arrival, and the carrier typically adds a clearance fee that the customer pays at the door.
Keep three money flows separate. VAT on the sale is what you charge the customer. Import VAT is otherwise due when goods cross the border. Customs duty is a different charge entirely, governed by customs law rather than VAT law — a distinction that became far more important in 2026.
A consignment above EUR 150 falls outside IOSS. Standard import procedures apply, with import VAT and any duty handled at importation.
Can Businesses Use the SME Scheme, OSS and IOSS Together?
This is where precision pays. The answer is not a simple yes or no, and the Commission addresses each pairing differently.
SME Scheme and Union OSS
These coexist. A qualifying small enterprise can exempt supplies under the SME Scheme in its Member State of establishment and in chosen Member States, while using the Union OSS to declare supplies located in Member States where the exemption is not applied.
The restriction is jurisdictional. You cannot apply both the SME Scheme and the Union OSS at the same time in the same Member State. If exclusion from the exemption follows a threshold breach in one country, the Commission’s guidance points you to the Union OSS as the alternative there.
SME Scheme and IOSS
The Commission states these are mutually exclusive. A business applying the SME Scheme would have to opt out of it before using IOSS. If low-value imports into the EU are central to your model, that trade-off needs deciding early.
OSS vs IOSS — Different Transactions, Different Rules
The OSS vs IOSS question is usually a false choice. They address different supplies, so eligible businesses can hold both registrations and use each for what it covers. Union OSS handles goods already in the EU moving across internal borders. IOSS handles qualifying goods arriving from outside.
| Combination | Permitted | Conditions | Practical example | Common mistake |
| SME + Union OSS | Yes | Never both in the same Member State | Exempt supplies in Belgium under SME, OSS used for Spain | Assuming the EX number covers OSS countries too |
| SME + IOSS | No | Mutually exclusive; opt out of SME first | Seller must choose between exemption and import scheme | Registering for IOSS while still applying the exemption |
| Union OSS + IOSS | Yes | Separate registrations, separate returns | Intra-EU sales via OSS, imported parcels via IOSS | Declaring imported consignments in the OSS return |
| Union OSS + local VAT number | Yes | Local number needed where stock is held | FBA stock in Germany plus OSS for other markets | Cancelling local numbers after OSS registration |
SME Scheme vs OSS vs IOSS — Which Should Your Business Choose?
The honest framing is situational. Posed as SME scheme vs OSS vs IOSS, the question rarely has a single answer. Your establishment, turnover, stock locations and transaction types determine it, and plenty of businesses legitimately land on a combination.
| Business scenario | Potentially relevant regime | Key eligibility condition | Local VAT registration likely | Reporting | Main compliance risk |
| Small EU seller below national thresholds | SME Scheme | EU establishment plus both turnover tests | Often avoided in exempt countries | Quarterly turnover report | Assuming home eligibility travels abroad |
| Growing EU retailer across several markets | Union OSS | Eligible B2C supplies | Only where stock is held | Quarterly OSS return | Treating OSS as replacing all registrations |
| Non-EU seller shipping low-value goods | IOSS | Consignments up to EUR 150 | Not for IOSS itself | Monthly IOSS return | Intermediary requirement overlooked |
| Amazon FBA seller with multi-country stock | Union OSS plus local numbers | Stock location drives registration | Yes, in each storage country | OSS plus local returns | Domestic sales wrongly put through OSS |
| WooCommerce merchant, domestic and cross-border | Union OSS once the threshold is passed | Established in one Member State | Usually not | Domestic plus OSS | Misreading the EUR 10 000 trigger |
| SaaS or digital services provider | Union or non-Union OSS | Depends on establishment | Rarely | Quarterly OSS return | Customer location evidence |
| Seller via marketplace as deemed supplier | Marketplace handles certain VAT | Deemed-supplier conditions | Possibly, for own stock | Varies | Double-reporting facilitated sales |
| EU warehousing plus direct imports | OSS and IOSS together | Separate rules per flow | Yes, where stock sits | Quarterly plus monthly | Mixing the two return types |
A Practical Decision Tree
Work through these in order. Each answer narrows the field.
- Is your business established in the EU? No establishment rules out the cross-border SME exemption entirely.
- Are you selling goods, services, or both? Services and goods follow different OSS routes.
- Are your customers consumers or businesses? OSS and IOSS address B2C supplies.
- Where are the goods when the sale happens? Stock inside the EU points to OSS; stock outside points to IOSS.
- Are goods imported from outside the EU? If yes, check the consignment value.
- Is the consignment EUR 150 or less, and free of excise goods? Only then is IOSS available.
- What is your Union-wide annual turnover? Above EUR 100 000 removes the SME option.
- Do you meet the national threshold in each target country? This must be checked individually.
- Have your cross-border B2C supplies passed EUR 10 000? That changes where VAT is due.
- Do you hold stock, or have a fixed establishment, anywhere else? Local obligations may persist regardless.
No scheme here replaces every other VAT obligation. Each simplifies one part of the picture.
Working out which combination fits your actual sales data is where most teams stall. OSS and IOSS registration support from VATCompliance by Lappa covers Union OSS, non-Union OSS and IOSS, including acting as an EU intermediary for non-EU businesses that need one.
EU VAT Thresholds Explained — EUR 10 000 vs EUR 100 000 vs EUR 150
Confusing these three numbers causes more trouble than any other issue in this area. The EU VAT thresholds below measure different things on different bases.
| Threshold | What it measures | Basis | Applies to | If exceeded |
| EUR 10 000 | Place of supply for certain cross-border B2C supplies | Annual, combined, excluding VAT | TBE services and intra-EU distance sales dispatched from the Member State of establishment | Destination VAT applies without exception |
| EUR 100 000 | Eligibility ceiling for the cross-border SME exemption | Annual Union-wide turnover, current and previous year | EU-established small enterprises | Exclusion from the scheme in all Member States, with quarantine |
| EUR 150 | Eligibility limit for the import scheme | Intrinsic value per consignment | Distance sales of imported goods | IOSS unavailable; standard import rules apply |
Two misconceptions are worth killing off. EUR 10 000 is not a universal EU VAT exemption — it only shifts where VAT is due, and only for the supplies and conditions listed above. EUR 100 000 has nothing to do with OSS eligibility; it governs an exemption, not a filing route.
What Changed for EU VAT and IOSS in 2026?
Customs law changed in 2026, and the change is frequently misreported as a VAT change. It is not.
As from 1 July 2026, the customs duty exemption threshold of EUR 150 was abolished. Under Council Regulation (EU) 2026/382 of 11 February 2026, a temporary fixed customs duty of EUR 3 applies per item supplied as a distance sale of imported goods in a consignment not exceeding EUR 150. Note the wording: per item supplied as a distance sale of imported goods, which is not automatically the same as per parcel or per physical unit.
Here is the part that matters for scheme eligibility. Removing the customs duty relief did not remove the EUR 150 ceiling for IOSS. Duty relief and VAT scheme eligibility are separate legal concepts in separate instruments. IOSS continues to apply to qualifying consignments of EUR 150 or less.
The Commission published VAT guidelines on the EUR 3 duty on 16 June 2026, as an addendum to the e-Commerce explanatory notes. Those guidelines also address the VAT treatment of an announced Union handling fee on distance sales of imported goods, applicable from November 2026 at the earliest. Treat that handling fee as announced rather than in force, and verify its status before building it into pricing.
What EU VAT for Ecommerce Looks Like After the Change
EU VAT for ecommerce sellers now means landed-cost calculations carrying a duty line that did not exist before July 2026. Margins on very low-value items are most exposed, since a fixed charge bites hardest on a EUR 12 order. Checkout logic, carrier instructions and customs data quality all need review, and the Commission guidelines are the source to work from rather than secondary commentary.
How to Register and Stay Compliant
A structured sequence beats reacting to each deadline. Work through it in order.
- Map sales by country and by sales channel.
- Identify your establishment, and any fixed establishments.
- Separate B2B from B2C transactions.
- List every stock location and dispatch country.
- Split intra-EU sales from imported sales.
- Compare turnover against the Union and national limits.
- Determine which regimes are legally available to you.
- Check whether local VAT numbers are still required.
- Complete the relevant registrations or the prior notification.
- Configure checkout tax logic and destination VAT rates.
- Diarise every reporting deadline, quarterly and monthly.
- Reconcile transactions, returns, refunds and marketplace records.
- Monitor thresholds and eligibility through the year, not at year end.
VAT Compliance for Online Sellers — Common Mistakes
Strong VAT compliance for online sellers mostly means avoiding a short list of recurring errors.
- Confusing a VAT exemption with simplified VAT filing.
- Assuming OSS removes every national VAT obligation.
- Reading EUR 10 000 as a universal EU exemption.
- Applying the SME exemption without confirming national eligibility.
- Using IOSS for consignments above EUR 150, or for excise goods.
- Ignoring stock locations and marketplace deemed-supplier rules.
- Mixing customs duty rules with VAT rules.
OSS and IOSS Registration Steps
Both routes share a shape: one Member State of identification, one registration, then periodic returns. OSS and IOSS registration differ mainly in who may apply and how often you file — quarterly for OSS, monthly for IOSS, with an intermediary generally required for non-EU businesses using the import scheme.
Simplify Your EU VAT Compliance. Managing obligations across several European markets? VATCompliance by Lappa supports registration and reporting workflows for VAT, OSS and IOSS, with VAT registration handled separately where local numbers are still required. Software helps you organise data and meet deadlines. It does not determine your legal eligibility, and it does not replace advice on your specific facts — talk to the team where the position is genuinely unclear.
Key Takeaways
- The SME Scheme exempts. OSS and IOSS simplify declaration of VAT that remains due.
- Cross-border SME access needs EU establishment, EUR 100 000 Union turnover or less, and compliance with each national threshold.
- The EX number starts the exemption from the date it is confirmed, not the date you applied.
- SME and Union OSS coexist, but never in the same Member State. SME and IOSS are mutually exclusive.
- OSS never removes the need for local registration where you hold stock.
- The EUR 150 customs duty relief ended on 1 July 2026, but the EUR 150 IOSS limit remains.